
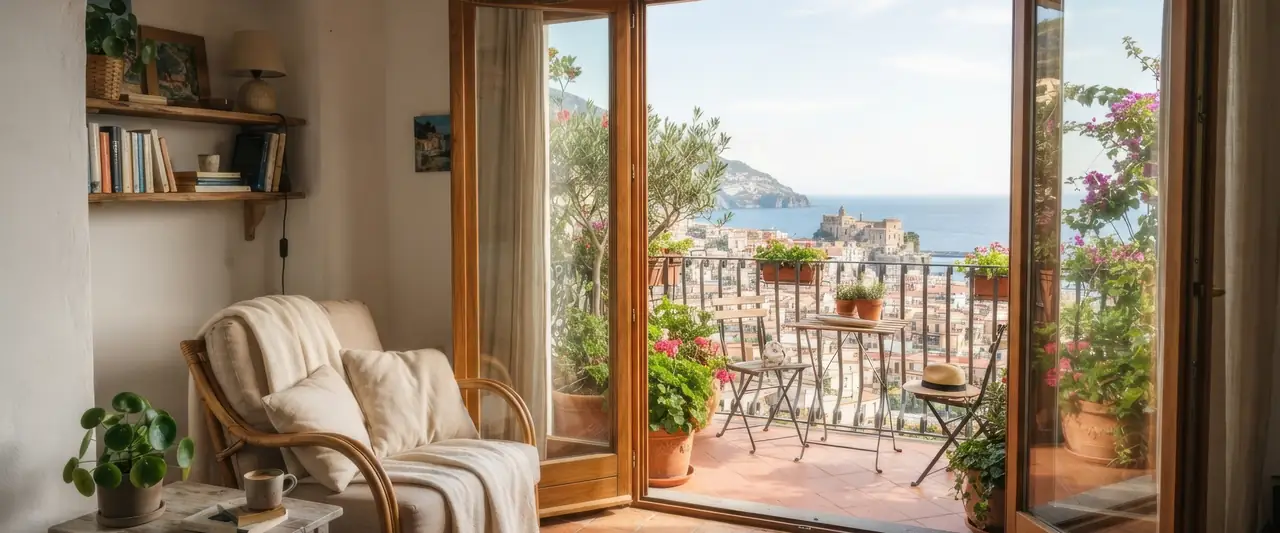
Holiday Letting
For those who manage holiday-let properties as a business: third-party liability, property damage and business continuity.
Why insure your holiday-let property
A home policy won't do
Home insurance is designed for someone who lives in the property. Letting it out short-term to strangers is a different activity, and most policies exclude it.
You're liable to the guest
If someone is injured on the property, or a fault of yours floods the neighbour, the claim is made against the owner, not against the guest staying there.
The days you're not letting
If a claim leaves the property unusable, you lose the bookings already confirmed and have to find alternative accommodation for the guests who were coming. That can be insured too.
What's covered
The specific cover and its limits depend on the insurer and the type of policy you take out. At Retuerto y Asociados we put it in writing before you decide.
Liability
Damage to guests, neighbours and third parties arising from ownership of the property, including legal expenses cover and provision of bonds.
Water damage and weather events
Leaks, seepage, dripping, flooding, wind, rain and hail, including locating the source of the fault.
Fire, explosion and lightning
Includes smoke, impact damage, firefighting costs and debris removal, and total loss of the property.
Theft and vandalism
Theft, forcible theft and burglary within the property, replacement of keys and locks, and damage caused by guests.
Glass and electrical damage
Breakage of glass, sanitaryware, ceramic hobs, marble surfaces and solar panels, and electrical faults in appliances.
Loss of use
If the property can't be used after a claim, it covers alternative accommodation for the period agreed in the policy.
Home assistance
Plumbing, locksmith, electrical and glazing services, with tradespeople who attend even if you're hundreds of kilometres away.
Legal protection
Advice and defence in disputes arising from letting and from ownership of the property.
Is it compulsory?
Regulation of holiday lets is set at regional level in Spain and varies from one area to another. In most, at the very least, liability insurance is required in order to register the property.
That legal minimum covers damage to third parties and nothing else: it doesn't compensate you if a tenant wrecks the furniture or a water leak ruins the kitchen. That's why it's usual to take out a full holiday-let policy, which includes compulsory liability cover and also protects the property itself.
At Retuerto y Asociados we tell you what the regulations that apply to your property require, and how far it's worth covering yourself in your particular case.
Unexpected costs add up
Once a property is let out, the unexpected stops being hypothetical. A burst pipe, a break-in, a storm that damages the house until it's uninhabitable: any of these can happen just as guests are on their way.
That's when the cost nobody had budgeted for turns up: you have to rehouse them, refund the booking, or both. With a holiday-let policy, that money doesn't come out of your own pocket.
And because every property is different — a flat in the centre, a villa with a pool, an apartment within a residents' association — the policy is tailored to what you actually have: sum insured for the building and for the contents, liability limits and optional cover.
Frequently asked questions
How do I take it out?
The simplest way is through a brokerage: we compare policies from several insurers for your type of property and show you what each one covers and what it leaves out, with the limits in writing.
What exactly does the liability cover include?
Damage caused to third parties, defence and legal assistance in proceedings, and the provision of bonds if a court requires them. It doesn't compensate for damage to your own property: that needs damage cover.
What risks do I run by letting?
Mainly two: the property suffering damage — through use, carelessness or vandalism — and damage originating there affecting the residents' association or a neighbour. In the second case, the compensation can comfortably exceed what you earn from the letting.
What types of property can be insured?
Flats, apartments, houses and villas. Also outdoor areas: pool, garden or terrace, provided you tell us about them when taking out the policy so they're included in the risk description.
What an Insurance Broker Really Is
A broker is the expert who acts between the insurance company and the client, representing the insured party and their interests, not solely the insurer's.
We are the only professionals legally qualified to advise with strict independence and impartiality from insurance companies.
- We compare the marketAdvice based on an objective analysis of contracts from a sufficient number of insurance companies.
- It costs you nothingThe broker is paid by the insurer in the form of commissions. In principle, the service costs the client nothing.
- We handle everythingFrom taking out the policy through to the claim, if one arises.
- We defend your interestsAgainst the insurer, in the same way a lawyer would.
Other Insurance for Shops and the Self-Employed
Shop multi-risk
The premises, contents, stock and the activity carried out inside, in a single policy.
View insurance
Rent guarantee
For landlords of homes and premises: guaranteed rent, eviction proceedings and damage.
View insurance
Liability
General, employer's, premises and product liability against third-party claims arising from your activity.
View insurance
Life
Protects your family and your business in the event of the death or permanent disability of the business owner.
View insurance
Health
Health policies for the self-employed and for small workforces, with group terms.
View insurance
Accidents
Accident cover for the self-employed and their employees, including cover under the applicable collective agreement.
View insuranceWhat People Tend to Believe, and What Actually Happens
Five ideas we hear often that turn out to be costly the day there's a claim.
"Going it alone works out cheaper."
A broker costs you nothing: they're paid by the insurer. And they compare several companies at once that you'd otherwise have to approach one by one.
"All policies are the same."
Two policies at the same price can have very different limits, excesses and exclusions. What matters is what the terms say on the day of the claim.
"The broker works for the insurer."
The broker represents the insured and their interests. The person who represents the company is its agent, which is a different role entirely.
"If I have a claim, I'll sort it out myself."
How the report is opened and documented shapes the whole process afterwards. We handle it, and the claim too.
"Switching insurer is a hassle."
We handle it, including cancelling the previous policy in good time so it doesn't renew on its own.
"The compulsory cover is enough for me."
The legal minimum covers what you cause to others, not what happens to you. That's the difference between a scare and a real problem.
Shall we prepare a holiday-let insurance quote for you?
Tell us about your situation and we'll send you a comparison with the best options on the market, the best support for making the right decision.
- No obligationWe give you the price and the cover; you decide.
- No costAs brokers we're paid by the insurer, not you.
- Fast responseDuring office hours, usually the same day.
What questions do you have?
We'll get back to you with a holiday-let insurance quote and a tailored comparison.
Can’t see the form? Open it in a new window.
Prefer to talk? Call us on 922 235 203 or message us on WhatsApp at 667 420 381.