
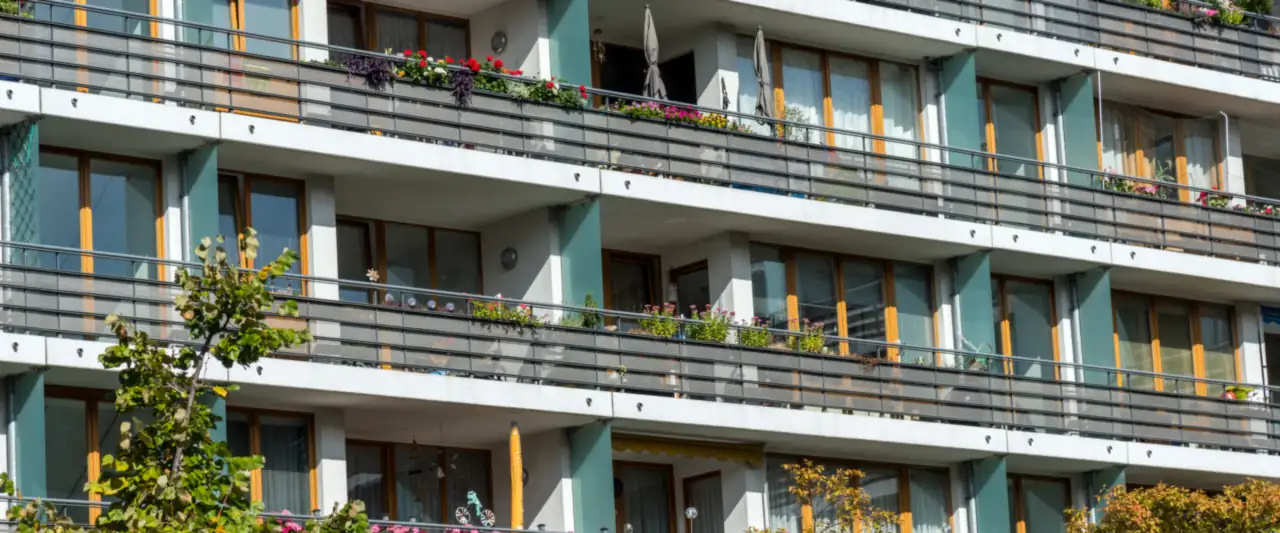
Homeowners' Associations
Protect the homeowners' association building: structure, building fabric and third-party liability.
What does it involve?
A homeowners' association policy protects the building against any incident that may affect the structure or the building fabric. It works like a home insurance policy, but excluding the interior of each individual home.
It should also cover the liability arising from damage or injury caused to other people, such as a piece of balcony or a railing falling or coming loose.
Typical cover
- Building fabric and communal areas
- Water damage
- Fire, explosion and lightning
- Weather-related events
- Electrical damage
- Broken glass
- Third-party liability of the association
- Legal expenses and damage claims
- 24-hour assistance
What an insurance broker really is
The broker is the expert who acts as an intermediary between the insurance company and the client, representing the insured party and their interests rather than the insurer alone.
We are the only qualified professionals legally authorised to advise with strict independence and impartiality from insurance companies.
- We compare the marketAdvice based on an objective analysis of policies from a sufficient number of insurance companies.
- It costs you nothingThe broker is paid by the insurer in the form of commissions. In principle, the service costs the client nothing.
- We handle everythingFrom taking out the policy through to the claim, should one arise.
- We defend your interestsBefore the insurance company, in the same way a lawyer would.
Other personal insurance
Car
From third-party cover to fully comprehensive, with roadside assistance, a replacement vehicle and legal expenses.
View insurance
Motorbike
In Spain, motorbike and moped insurance is compulsory in order to ride legally.
View insurance
Electric scooter
Third-party liability to ride, plus the option to also cover accidents and the scooter itself.
View insurance
Home
Water damage, broken glass, fire, weather events, short circuits, breakdowns and theft.
View insurance
Holiday letting
Holiday-let properties carry risks that a standard home policy doesn't cover.
View insurance
Rent guarantee
You still receive the rent even if the tenant stops paying, with legal proceedings and damage covered.
View insuranceWhat people tend to believe, and what actually happens
Five ideas we hear often that prove costly the day there's a claim.
"Going it alone works out cheaper."
The broker costs you nothing: the insurer pays them. And they compare several companies at once, which you would otherwise have to approach one by one.
"All policies are the same."
Two policies at the same price can have very different limits, excesses and exclusions. What matters is what the terms say on the day of the claim.
"The broker works for the insurance company."
The broker represents the insured party and their interests. It is the agent who represents the company, which is a different role altogether.
"If I have a claim, I'll sort it out myself."
How the claim is opened and documented shapes everything that follows. We handle it for you, and the claim itself too.
"Switching insurer is a hassle."
We manage it for you, including cancelling the previous policy in time so it doesn't renew automatically.
"The compulsory insurance is enough for me."
The legal minimum covers what you cause to third parties, not what happens to you. That's the difference between a scare and a real problem.
Shall we prepare a homeowners' association quote for you?
Tell us about your situation and we'll send you a comparison of the best options on the market — the best support for the right decision.
- No obligationWe give you the price and the cover; you decide.
- No costAs brokers, we are paid by the insurer, not by you.
- Fast responseDuring office hours, usually the same day.
What questions do you have?
We'll get back to you with a homeowners' association quote and a tailored comparison.
Can’t see the form? Open it in a new window.
Prefer to talk? Call us on 922 235 203 or message us on WhatsApp at 667 420 381.